

Andrew Pyle
December 08, 2023


Setback in the energy patch creates opportunities
There has been a bit of a reality check in stocks so far this month following the surge in November. While the major indices are still in the green, gains in December have thus far been very modest. In the case of the TSX, we are basically flat, even though there have been strong moves in communications, real estate and utilities. Indeed, 9 of the 11 major sub-groups have moved higher this month, but two sectors have almost completely offset these gains – materials and energy. The latter is down close to 4%, after what was looking to be a solid second half.
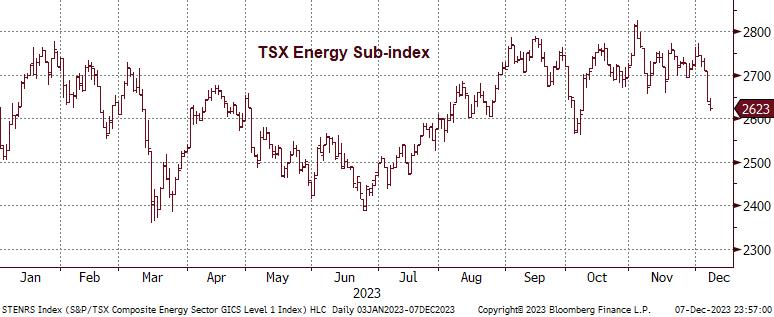
The sell-off in the patch became more pronounced in the last few sessions, taking the TSX sub-index to just above 2600 – right on top of the 200-day moving average. We had dipped below this line back in early October, before vaulting to the best levels in a year. That said, even with this month’s slide, the group is still the second-best performer during the second half (+5.5%) after tech (+11.5%).
The main reason behind the recent pullback is that crude oil prices have come off the boil in a big way. In the first quarter, when WTI futures had fallen from the 2022 highs above $120/barrel down to almost $60, the street became extremely bearish. The $60 level, however, had provided firm support in the second half of 2021 and it did so again this year. OPEC+ implemented production cuts (though almost entirely by Saudi Arabia) and demand didn’t collapse as some had feared, mainly because most of the world didn’t slip into recession.
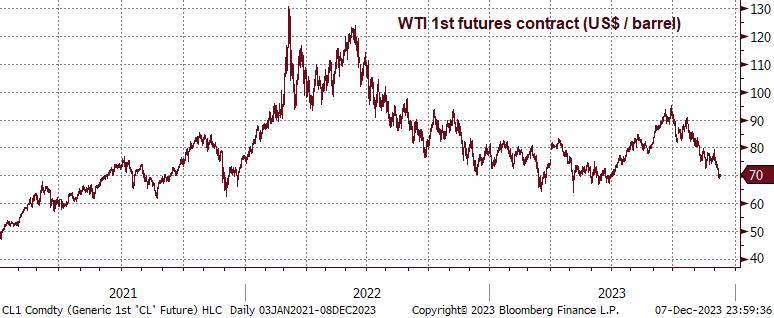
This week, WTI futures slipped below the $70 mark, reversing all of the gains made since the end of June. The roughly $6 decline in the first six days of the month makes this the worst week for crude since 2018. This has surprised investors, especially since the latest OPEC+ meeting resulted in a decision to strengthen production cuts and Saudi Arabia has even suggested extending the cuts to March. The problem is that other countries are pumping even more crude out of the ground, including the U.S. That is raising concerns of a supply glut at a time when Chinese demand is weaker.
Before we get too gloomy on the outlook, it is important to remember that there are factors at play that will support oil prices and hence the revenues of producers. Yes, we are in the middle of a transition away from fossil fuels, but it doesn’t work like a light switch and this will require continued investment in traditional energy to maintain supplies. During this transition, however, companies are less willing to plow the same amount of capital into new drilling and exploration. Instead, cash flow is being redirected to dividends and share buybacks.
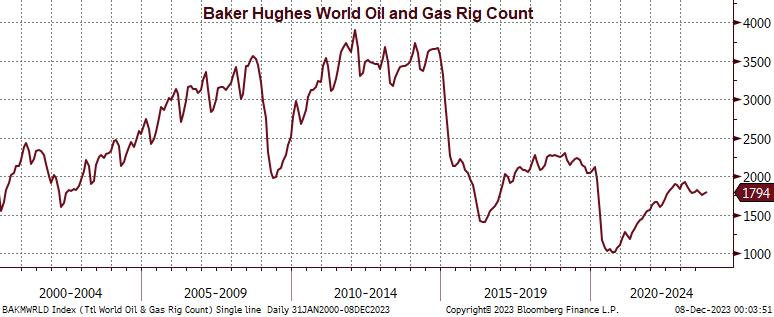
The above chart shows the Baker Hughes total global oil and natural gas rig count of the last 20 years. While we saw a recovery after the pandemic, the peak in February this year fell short of the best level in 2019 and well below 2014 highs. From February, the total number of rigs is down about 6% and the decline in the U.S. is about three times larger. Less drilling ultimately means constrained supply and, while demand may appear to be softening, that situation isn’t going to stay that way. China is going to take further steps to bolster its economy and, when interest rates start to decline in 2024, economic demand in North America will also be supported.
Still, for many investors, the experience with energy companies over the years has been frustrating. Some people talk of lost decades in certain asset classes. Well, the TSX energy patch isn’t that much better than where it was 20 years ago. At that point in time, we were just about to venture into discussions over “peak oil” and crude prices were going to soar to $200 and beyond. In December 2003, WTI futures were trading around $30 and the TSX energy sub-index was close to 1400. So, over 20 years the index rose by 83%, which works out to a compound average growth rate of 3%. Not awful, but if we had bought a 20-year Government of Canada bond back then, we would have scooped an annual yield of over 5%.
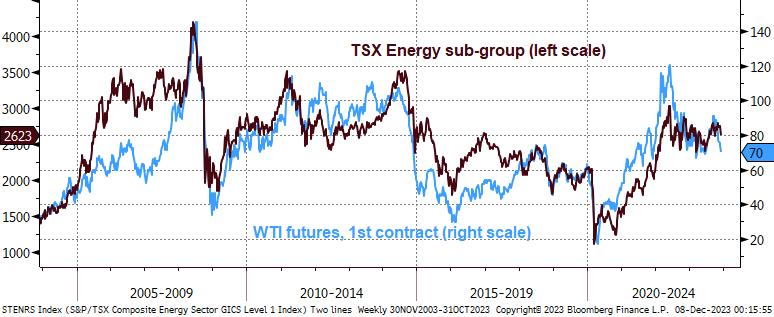
If you take the view that crude prices will find a floor around $60 and that relaxation of aggressive monetary policy tightening eventually allows for demand growth later in 2024, then an argument can be made for higher valuations in the energy patch going forward. I would argue that companies with a higher concentration in natural gas could do even better over the medium term. Production, especially in the U.S., has seen a significant increase and technological enhancements to extraction have added to supply. Assuming prices stabilize above $60 and we remain in a $60-90 range, then this added production is going to generate growth in revenues and also earnings. This will depend on cost inflation continuing to drop.
While the story for oil looks good, I believe that natural gas is emerging as the more viable bridge in the transition to zero emissions as it is cleaner than coal and oil. Prices remain depressed, pending the weather outcome this winter, but increased demand from power generation offers up an additional support above the US$2 / MMBTU level.
As I discussed on BNN this week, there are definitely some names worth looking at in the current environment based on position in the market and valuations. As always, I am more than happy to discuss any of the points made in the newsletter and answer any questions on our economic and market views, and how we are helping high net worth individuals and families navigate these waters.
On behalf of the Pyle Wealth Advisory team, have a wonderful weekend.
Andrew Pyle
CIBC Private Wealth consists of services provided by CIBC and certain of its subsidiaries, including CIBC Wood Gundy, a division of CIBC World Markets Inc. “CIBC Private Wealth” is a registered trademark of CIBC, used under license. “Wood Gundy” is a registered trademark of CIBC World Markets Inc. This information, including any opinion, is based on various sources believed to be reliable, but its accuracy cannot be guaranteed and is subject to change. CIBC and CIBC World Markets Inc., their affiliates, directors, officers and employees may buy, sell, or hold a position in securities of a company mentioned herein, its affiliates or subsidiaries, and may also perform financial advisory services, investment banking or other services for, or have lending or other credit relationships with the same. CIBC World Markets Inc. and its representatives will receive sales commissions and/or a spread between bid and ask prices if you purchase, sell or hold the securities referred to above. © CIBC World Markets Inc. 2023.CIBC Wood Gundy, a division of CIBC World Markets Inc. Insurance services are available through CIBC Wood Gundy Financial Services Inc. In Quebec, insurance services are available through CIBC Wood Gundy Financial Services (Quebec) Inc.
The CIBC logo and “CIBC Private Wealth” are trademarks of CIBC, used under license. “Wood Gundy” is a registered trademark of CIBC World Markets Inc.
These are the personal opinions of Andrew Pyle and Pyle Wealth Advisory and may not necessarily reflect those of CIBC World Markets Inc.
Related posts
Andrew Pyle
March 22, 2024
History is not a guarantee of the future, but it can be a guide
History can provide some clues for the direction that economies and markets will take. Some are looking at the tech boom/bust for exactly that these days.
Read moreAndrew Pyle
January 31, 2025
No disruptions please, we're central bankers
The Bank of Canada and Federal Reserve held their first policy meetings of 2025 and while the decisions and messaging were different, they share one source of uncertainty in common.
Read more