

Andrew Pyle
July 26, 2024


An eventful July could end the same
After this week’s market activity, not to mention the political events of last Sunday, investors are probably hoping for some quieter summer days as we head into August. Market volatility, as measured by the CBOE VIX index, departed from its sleepy levels near 12 at the start of July and spiked to over 18 going into Friday. This is the highest it has been since April, when it pushed above 20. As I commented on BNN and in this week’s conference call, the volatility pattern has shifted from what we originally thought due to not only political developments but a market that had set the bar high on earnings.
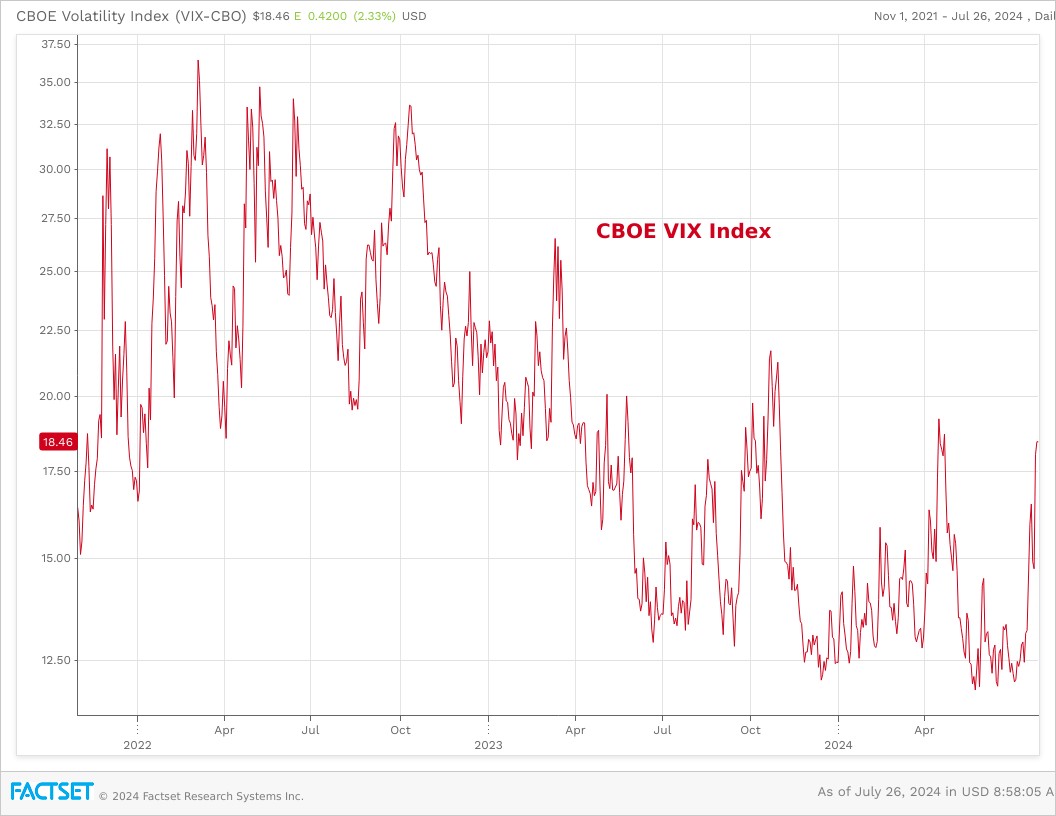
Source: FactSet Research Systems
U.S. earnings season is now in full gear and the misses by two of the “mag-7” companies (Tesla and Alphabet) were a catalyst behind a sizable pullback in not only tech, but other segments of the market. Next week, we get Microsoft, Meta Platforms, Apple, Amazon (Nvidia doesn’t report until August 28th), but key players in all sectors will also be releasing results and these are going to be put under the microscope for signs that earnings and/or revenue growth has hit a wall.
If so, this would support the view that the U.S. economy continues to slow, which is good and bad news. Good in that weaker activity should allow inflation to continue its downward glide, thus paving the way for the Fed to lower rates. Bad, in that the Fed is still expected to wait until September before delivering its first cut. This week, former NY Fed President Bill Dudley, who I once interviewed with for a job at Goldman Sachs, suggested that failure to lower rates at next Wednesday’s FOMC meeting could threaten a recession. Again, few economists are predicting a move next week, but we do anticipate that they will offer guidance in the statement and Powell’s Q&A that September is fully in play. What if they surprise the market with a quarter-point cut? That would be interesting and likely increase volatility, regardless of market direction. On the one hand, this could be taken as a growth-positive step that ends up supporting stock valuations. However, markets don’t like surprises and they could interpret such a decision as reflecting concern at the Fed over the real state of the economy. Stay tuned.
Outside of the Fed and earnings, the main focus in terms of economic fundamentals will be the July payrolls report next Friday. Coming off a 206K monthly increase in June, the street consensus is for a more modest gain of 180K, with the unemployment rate holding at 4.1%. If the Fed does leave rates unchanged next week, there will be one more payrolls kick at the can before the September FOMC meeting. We will also be watching the July consumer confidence report on Tuesday, as well as the manufacturing PMI report on Thursday. The only key indicator for Canada next week will be the May GDP report on Wednesday – pretty much ancient history in the context that the Bank of Canada has already given us its update of where it sees the economy, following this week’s decision to cut rates a second time.
On behalf of the Pyle Wealth Advisory team, have a wonderful weekend.
Andrew Pyle
CIBC Private Wealth consists of services provided by CIBC and certain of its subsidiaries, including CIBC Wood Gundy, a division of CIBC World Markets Inc. The CIBC logo and “CIBC Private Wealth” are trademarks of CIBC, used under license. “Wood Gundy” is a registered trademark of CIBC World Markets Inc.
Andrew Pyle is an Investment Advisor with CIBC Wood Gundy in Peterborough. The views of Andrew Pyle do not necessarily reflect those of CIBC World Markets Inc.
This information, including any opinion, is based on various sources believed to be reliable, but its accuracy cannot be guaranteed and is subject to change. CIBC and CIBC World Markets Inc., their affiliates, directors, officers and employees may buy, sell, or hold a position in securities of a company mentioned herein, its affiliates or subsidiaries, and may also perform financial advisory services, investment banking or other services for, or have lending or other credit relationships with the same. CIBC World Markets Inc. and its representatives will receive sales commissions and/or a spread between bid and ask prices if you purchase, sell or hold the securities referred to above. © CIBC World Markets Inc. 2024.
If you are currently a CIBC Wood Gundy client, please contact your Investment Advisor.
Related posts
Andrew Pyle
October 30, 2026
The Road Less Hiked
The road less hiked made all the difference this week, with the BoC opting to move while the Fed preferred to linger at the fork.
Read moreAndrew Pyle
October 23, 2026
Death and Taxes: Agonizing Over the Wrong Bill
The bill most families worry about after death is often not the one that costs the most. Good planning starts with knowing the difference.
Read more