

Andrew Pyle
July 24, 2024


Bank of Canada rides to the economy's rescue
While most economists expected the Bank of Canada to cut rates for a second consecutive time today, investors wondered whether officials might be concerned about the implications of lowering rates when U.S. rates held steady, with respect to the currency and inflation. That apparently is not the case and this morning we got a second straight quarter-point reduction in the Bank’s overnight target, taking it to 4.5%.

The key drivers behind today’s decision include the continued retreat in headline inflation, which fell to 2.7% in June and while core inflation did show a surprising uptick. The accompanying statement again made note of signs of slack in the labour market and moderating wage growth. In addition, the Bank sees potential output growth exceeding the actual growth of the economy, implying that excess supply is increasing. This supports the Bank’s forecast that core inflation measures will decline to around 2.5% in the second half of the year and move towards its 2% target in 2025. The Bank is, however, still mindful of the elevation in shelter costs and other services prices and repeated that it will continue to monitory the effects of these areas on overall inflation.
That said, it is clear that the Bank’s assessment of risk has shifted more towards weakness in the economy and away from inflation. It’s recent Business Outlook Survey, released last week, pointed to weak demand having a negative impact on investment and hiring plans and that most companies saw wage growth and inflation moderating. In the Survey of Consumer Expectations, it found that most consumers reported lower spending and pessimism over their future financial conditions. With three more meetings this year, we would anticipate at least one more move on rates and possibly two.
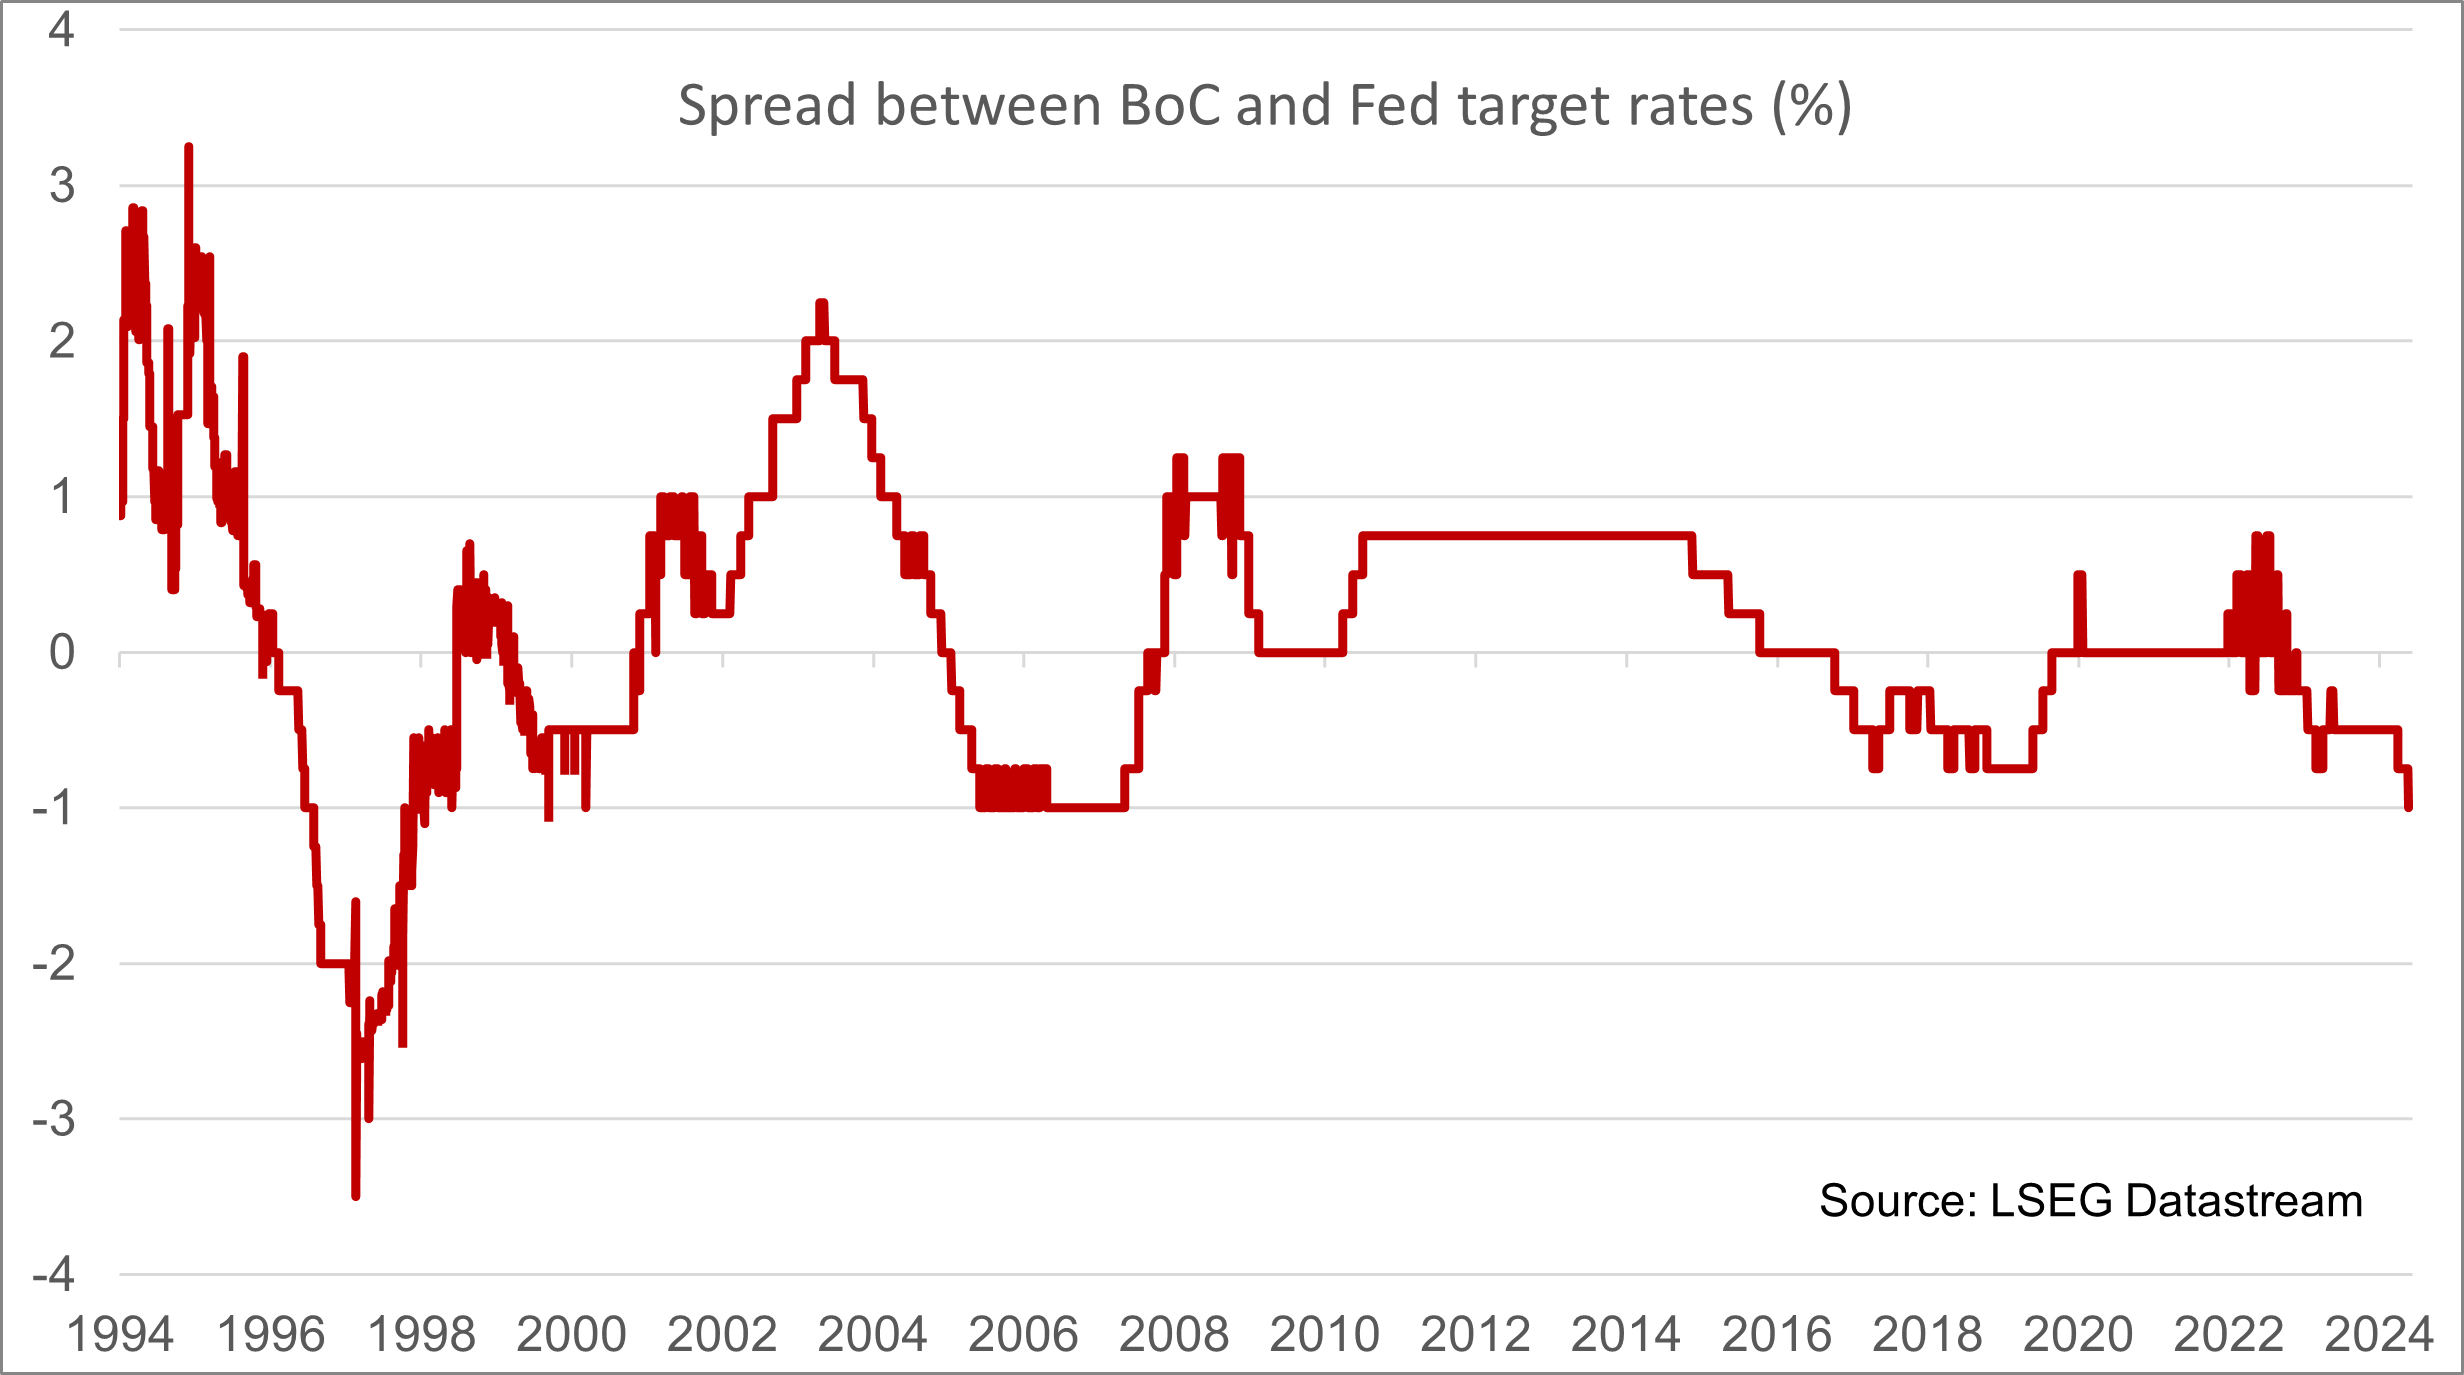
Of course, the Bank does not comment on the Canadian dollar nor comparisons between how it’s policy stance and that of other central banks. Market participants, however, have focused in on the fact that today’s cut takes the spread between the Bank’s overnight target and the Fed funds rate to minus 1%, which is the widest it has been since 2007, as the above chart shows. The next FOMC meeting is next week, though few economists expect the Fed to lower rates.
As I mentioned in yesterday’s conference call, we may likely see another cut in September and if the guidance next week supports that, it is possible that the downward pressure on the Canadian dollar will be limited. We did see the Loonie sell off modestly this morning and it is getting close to its weakest levels it slipped to in April, near 72.30 U.S. cents. If this level fails in the weeks leading up to the September FOMC meeting, then it would be a break of 72 cents in play. At that point, economists and possibly Bank officials might become more concerned that this could fuel inflation, via higher import prices.
There are three policy meetings remaining this year and our view remains that we will see at least one more quarter-point cut out of them.
On behalf of the Pyle Wealth Advisory team, have a great rest of the week.
Andrew Pyle
CIBC Private Wealth consists of services provided by CIBC and certain of its subsidiaries, including CIBC Wood Gundy, a division of CIBC World Markets Inc. The CIBC logo and “CIBC Private Wealth” are trademarks of CIBC, used under license. “Wood Gundy” is a registered trademark of CIBC World Markets Inc.
Andrew Pyle is an Investment Advisor with CIBC Wood Gundy in Peterborough. The views of Andrew Pyle do not necessarily reflect those of CIBC World Markets Inc.
This information, including any opinion, is based on various sources believed to be reliable, but its accuracy cannot be guaranteed and is subject to change. CIBC and CIBC World Markets Inc., their affiliates, directors, officers and employees may buy, sell, or hold a position in securities of a company mentioned herein, its affiliates or subsidiaries, and may also perform financial advisory services, investment banking or other services for, or have lending or other credit relationships with the same. CIBC World Markets Inc. and its representatives will receive sales commissions and/or a spread between bid and ask prices if you purchase, sell or hold the securities referred to above. © CIBC World Markets Inc. 2024.
If you are currently a CIBC Wood Gundy client, please contact your Investment Advisor.
Related posts
Andrew Pyle
October 30, 2026
The Road Less Hiked
The road less hiked made all the difference this week, with the BoC opting to move while the Fed preferred to linger at the fork.
Read moreAndrew Pyle
October 23, 2026
Death and Taxes: Agonizing Over the Wrong Bill
The bill most families worry about after death is often not the one that costs the most. Good planning starts with knowing the difference.
Read more